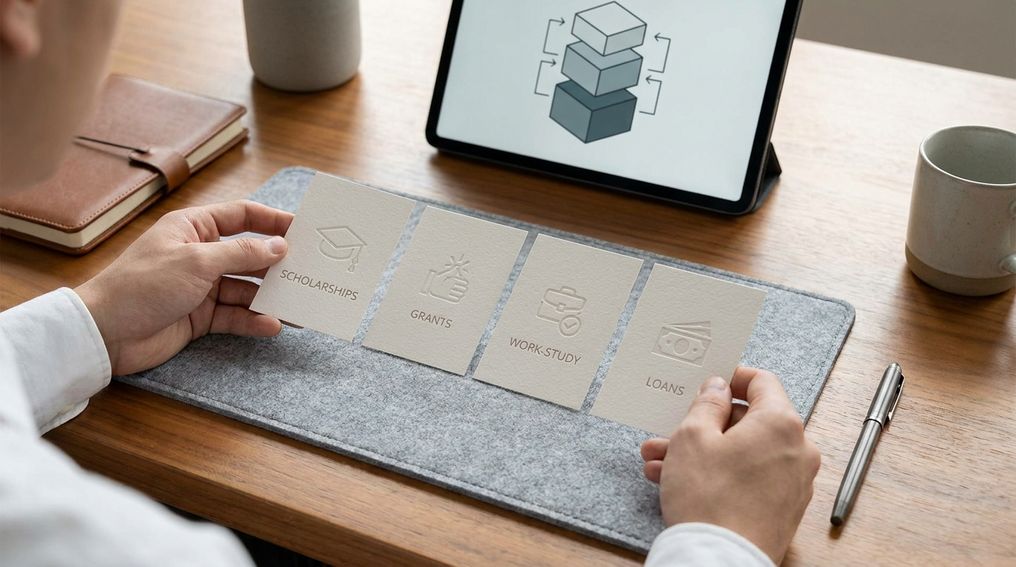
The best college funding order starts with aid that does not need to be repaid, then moves to earned money, then borrowed money only if you still have a gap. Your goal is to fill the college bill from the lowest-cost sources before you accept debt.
College funding gets confusing because the word “aid” can mean very different things. A grant can reduce your bill without repayment, a scholarship can reward achievement or background, work-study requires earning the money, and loans come with repayment obligations. This guide helps you choose the right sequence so you don’t leave free money untouched or borrow sooner than necessary.
Understanding The True Cost: Why Aid Does Not Mean Free
Financial aid is an umbrella term, not a promise of free money. It can include grants, scholarships, Federal Work-Study, federal student loans, state aid, institutional aid, and private loans. Some of those dollars reduce your cost with no repayment. Others create a future bill that follows you after school.
The most useful way to sort college funding is by cost to you. Gift aid sits at the top because it lowers your balance without requiring repayment. Earned aid comes after that because you trade time and work for money. Borrowed aid comes last because it helps you enroll now but creates repayment later.
This is where many families make an expensive mistake. They compare dollar amounts without comparing the terms behind those dollars. A large loan offer can look more comforting than a small scholarship, but the scholarship reduces your cost and the loan shifts the cost into the future. Your college funding order should always account for repayment, interest, eligibility rules, and timing.
Stop 1: The FAFSA Gateway Comes First
The Free Application for Federal Student Aid (FAFSA) should come before almost every other funding decision. It is the main gateway for federal aid, and many colleges and states use FAFSA information to decide whether you qualify for their own grants, scholarships, and work-study funds.
Do not skip the FAFSA because you assume your family earns too much. Some aid is need-based, but FAFSA data can still affect access to federal student loans, school-based aid, and state programs. Colleges can use the information to build your financial aid package, and skipping the form can narrow your options before you even compare offers.
Timing also matters. Some state and institutional aid pools are limited, so filing early can put you in a better position for funds that may run out. You do not need to know your final college choice before submitting the FAFSA. You can list schools, review aid offers later, and make a better decision with real numbers instead of guesses.
Stop 2: Grants Build The Need-Based Foundation
Grants should be one of the first funding sources you pursue after submitting the FAFSA. They are often based on financial need, and they usually do not need to be repaid when you meet the program’s rules.
The Federal Pell Grant is one of the best-known grant programs for undergraduate students with financial need. The maximum Federal Pell Grant award for the 2024–2025 award year is $7,395, though your actual award depends on eligibility factors and enrollment details. State grants and school grants can add another layer of support, especially when you apply early and meet each deadline.
Grants are valuable because they reduce the price before you start comparing loans. A grant does not require extra work hours during the semester, and it does not create future repayment. Review your aid offer carefully to see whether each grant renews automatically, requires a grade point average, or changes if your enrollment status changes. A grant that looks guaranteed can still have conditions attached.
Stop 3: Scholarships Fill Gaps Without Repayment
Scholarships should be pursued early and often, especially after you have submitted the FAFSA and gathered your college list. They are commonly awarded for merit, talent, academic interest, service, background, career goals, or local community involvement.
Start with scholarships from colleges because institutional awards can be larger and easier to apply for through the admission or financial aid process. Then look at local awards from community foundations, employers, civic groups, and professional associations. Smaller scholarships can be worth your time when the applicant pool is limited. A $750 local award may beat a national award with thousands of applicants if your odds are better.
Track deadlines, required essays, recommendation letters, renewal rules, and whether the scholarship is paid to you or directly to the school. Ask the college financial aid office how outside scholarships affect your aid package. Some schools reduce unmet need or loans first, which helps you. Others may adjust institutional aid, so you need to know the policy before you assume every outside dollar lowers the bill dollar for dollar.
Stop 4: Work-Study Gives You Earned Money Before Debt
Federal Work-Study provides part-time jobs for undergraduate and graduate students with financial need, but not every school participates. If you receive work-study in your aid offer, treat it as a chance to earn money rather than a guaranteed credit against your bill.
Work-study differs from a grant because you must work the hours to receive the money. The award amount is the maximum you can earn through eligible employment, not cash that automatically appears in your student account. Jobs may be on campus or with approved employers, depending on the school’s program and available positions.
This option belongs before loans in your college funding order because earned money can reduce what you need to borrow. It can also help cover books, supplies, transportation, and personal costs that do not always show up clearly on the tuition bill. Review the hourly wage, work schedule, location, and academic workload before accepting. A job that fits your class schedule can help; one that strains your study time can cost you in other ways.
Stop 5: Federal Student Loans Come After Free And Earned Aid
Federal student loans should come after grants, scholarships, and realistic work earnings. They can be useful, but they are still borrowed money that must be repaid with interest.
Within federal loans, subsidized loans are usually preferable to unsubsidized loans when you qualify. A subsidized loan is based on financial need, and the government pays the interest during certain periods, based on program rules. An unsubsidized loan is not based on financial need, and interest begins building according to the loan terms. That difference can affect your total repayment cost.
Federal loans usually belong ahead of private loans because they are designed for students and come with federal borrower protections. You still need to borrow carefully. Accept only what you need, compare the full cost of attendance with your actual bill, and avoid using loan money as a cushion for expenses you can reduce. Borrowing less now gives you more room after graduation.
What To Avoid Until The Very End: Private Student Loans
Private student loans should usually sit at the bottom of your funding list. They can help cover a remaining gap, but they often depend on credit approval, a co-signer, interest rate terms, and lender-specific repayment rules.
Before you consider a private loan, ask the financial aid office whether you have used all federal grant, scholarship, work-study, and federal loan options. Then revisit the school choice itself. A lower-cost college, tuition payment plan, community college transfer path, or use of 529 college savings plan funds can reduce the amount you need to borrow.
Private loans can also create risk for co-signers. A parent or other co-signer may be responsible if the borrower cannot pay. Terms vary by lender, so compare repayment options, interest rates, fees, co-signer release rules, and hardship options before signing. If the private loan is the only way to make the school affordable, pause and compare a lower-cost offer before committing.
How To Read Your Financial Aid Offer In The Right Order
A financial aid offer is not just a total number. You need to separate gift aid, earned aid, and borrowed aid before deciding whether the college is affordable.
Start by finding the full cost of attendance, including tuition, fees, housing, meals, books, supplies, transportation, and personal expenses. Then subtract grants and scholarships first. After that, estimate realistic earnings from work-study or other part-time work. Only then should you look at loans and decide whether the remaining balance is manageable.
Be careful when schools present loans beside grants and scholarships. A package that appears to cover the bill may still rely on borrowing. Compare offers by net price after gift aid, not by the largest total aid number. The cleanest offer is often the one that leaves the smallest gap after free money, not the one with the biggest loan line.
Should You Apply For Scholarships Before Or After FAFSA?
You should submit the FAFSA as early as you can, then keep applying for scholarships before and after admission decisions. The FAFSA opens doors to federal, state, and school-based aid, and scholarships can keep reducing your remaining cost.
You do not need to wait for every scholarship decision before filing the FAFSA. Treat FAFSA filing as the starting signal, then build a scholarship calendar around college deadlines, local deadlines, and national deadlines. Some scholarships require FAFSA information or proof of financial need, so finishing the form early can make those applications easier.
Scholarship applications can continue after you enroll, too. Many departments, alumni groups, and outside organizations offer awards for current college students. Keep a simple spreadsheet with deadlines, essay prompts, renewal rules, and award amounts. A steady process beats a last-minute scramble.
What Order Should You Apply For Financial Aid?
- Submit the FAFSA first.
- Pursue grants and scholarships.
- Use work-study earnings.
- Accept federal loans only if needed.
- Consider private loans last.
Make The Funding Order Work For Your Actual College Choice
The right college funding order protects you from treating every dollar the same. Start with the FAFSA, prioritize grants and scholarships, use earned money when it fits your schedule, and borrow only after you understand the remaining gap. Compare each college by net price after gift aid, not by the size of the aid package. If loans are doing most of the work, review lower-cost options before you sign. The best funding plan is the one that helps you enroll without handing your future self a bill that could have been smaller.